Your net worth is the one number that shows your whole financial picture: everything you own minus everything you owe. Your salary tells you what comes in, your budget tells you where it goes, and your net worth tells you whether you’re actually moving forward.
Here’s how to calculate your net worth, what to include, and how to track it in about five minutes a month.
What is net worth?
Net worth = total assets − total debts. Assets are things you own that have value: cash, savings, investments, retirement accounts, your home, your car. Debts (also called liabilities) are what you owe: mortgage, car loan, student loans, credit cards.
If you own more than you owe, your net worth is positive. If you owe more, it’s negative, which is very common when you’re young, just bought a home or still have student loans. What matters most is the direction it moves over time.
Step 1: List your assets
Write down every account and item of value, with today’s balance or a realistic value:
- Cash: checking accounts and cash at home.
- Savings: savings accounts, emergency fund, sinking funds.
- Investments: brokerage accounts, stocks, funds.
- Retirement: 401(k), IRA, pension or other retirement accounts.
- Property: your home at a realistic market value (be conservative).
- Vehicles: what the car would sell for today, not what you paid.
Skip everyday belongings like furniture, clothes and electronics. They rarely sell for much, and including them makes your net worth look better than it is.
Step 2: List your debts
Now list everything you owe, using the current balance (not the monthly payment):
- Mortgage
- Car loans
- Student loans
- Credit cards (the full balance)
- Personal loans, buy-now-pay-later and money owed to family
Step 3: Do the math
Add up each list and subtract debts from assets. Here’s an example:
| Assets | Value |
|---|---|
| Cash | $2,800 |
| Savings | $9,600 |
| Investments | $13,400 |
| Retirement | $33,200 |
| Home (market value) | $312,000 |
| Car | $13,400 |
| Total assets | $384,400 |
| Debts | Balance |
|---|---|
| Mortgage | $246,200 |
| Student loan | $14,600 |
| Car loan | $8,900 |
| Credit card | $900 |
| Total debts | $270,600 |
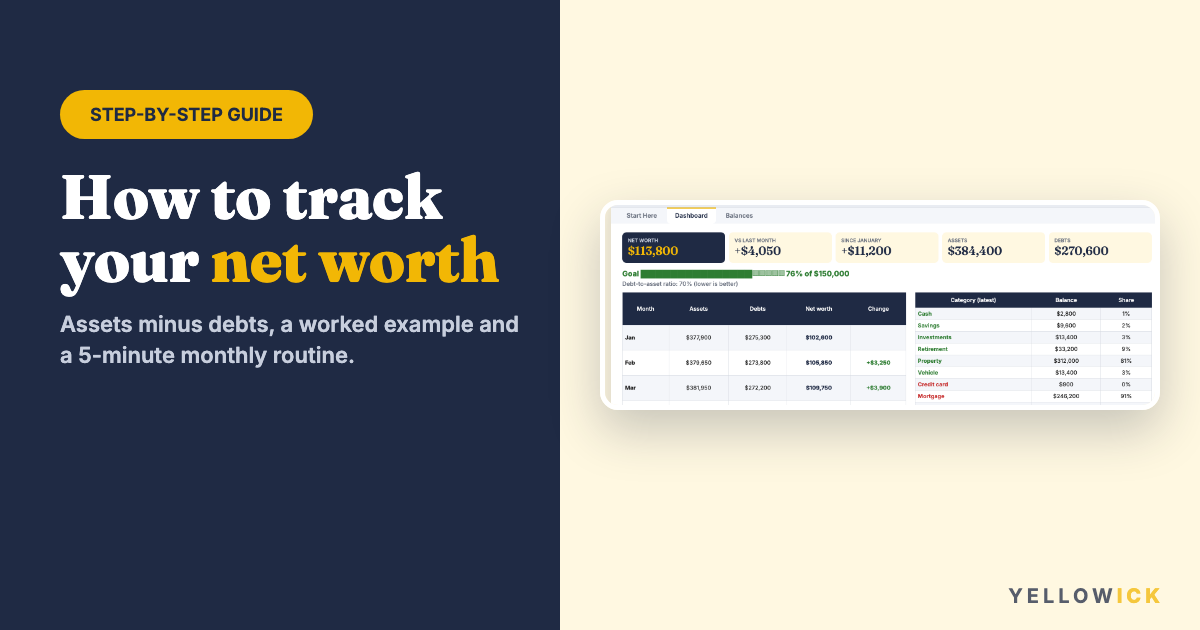
Net worth = $384,400 − $270,600 = $113,800.
Another useful number is the debt-to-asset ratio: total debts divided by total assets. Here it’s $270,600 ÷ $384,400 = 70%. It’s high because of the mortgage, which is normal for a recent home buyer. As the mortgage is paid down and savings grow, the ratio goes down.
Step 4: Track it every month
One calculation is a snapshot. The real value comes from repeating it. Pick a day, like the 1st of every month, and update each balance. It takes about five minutes once your list is set up. Here’s what four months of tracking could look like:
| Month | Net worth | Change |
|---|---|---|
| January | $102,600 | – |
| February | $105,850 | +$3,250 |
| March | $109,750 | +$3,900 |
| April | $113,800 | +$4,050 |
That’s +$11,200 since January. Seeing the number go up every month is surprisingly motivating, and when it goes down, you’ll notice right away and can find out why.
Don’t panic about short-term dips. Investment and home values move up and down. Look at the trend over six to twelve months, not a single month.
How to grow your net worth
- Spend less than you earn. A monthly budget makes sure there’s money left over every month.
- Pay off high-interest debt. Every dollar of credit card debt you pay off raises your net worth by a dollar. A debt payoff tracker shows your debt-free date.
- Build an emergency fund, so surprise bills don’t turn into new debt.
- Save and invest regularly, even small amounts, and let time do the work.
- Avoid new debt for things that lose value, like cars and gadgets.
Track your net worth in a spreadsheet
Our Net Worth Tracker for Google Sheets and Excel is built for exactly this: list your accounts once, type each balance once a month, and the dashboard shows your net worth, the change since last month and since January, your debt-to-asset ratio, a breakdown by category, a net worth goal with a progress bar and a chart for the whole year.
🎁 Free monthly budget template
Want to try this in a spreadsheet? Get our free one-month budget template for Google Sheets and Excel, with budget vs actual and an automatic 50/30/20 check. Get the free template →
Frequently asked questions
Should I include my home in my net worth?
Yes, include it at a realistic market value and include the mortgage as a debt. Some people also track a second number without the home to see their liquid net worth.
Is a negative net worth bad?
Not necessarily. It’s common with student loans or early in your career. Focus on making the number grow every year by paying down debt and saving.
How often should I calculate my net worth?
Once a month is enough for most people. Updating it more often just adds noise from daily market moves.
This article is for general information only and isn’t financial advice.